“Be Prepared: A Minimalist Guide to Building Your Emergency Fund”
Emergency Funds: A Minimalist Guide to Preparing for the Unexpected
As a minimalist, you know the value of living with less and focusing on what truly matters in life. However, when it comes to preparing for emergencies, having some financial cushion can be crucial. An emergency fund is an essential part of any budget or financial plan that can help you weather unexpected storms without derailing your progress towards your goals.
What Is an Emergency Fund?
An emergency fund is a sum of money set aside specifically for unforeseen expenses or income disruptions that may arise at any time. This could include anything from medical bills, car repairs, home maintenance costs, job loss, or other emergencies that require immediate attention and expense.
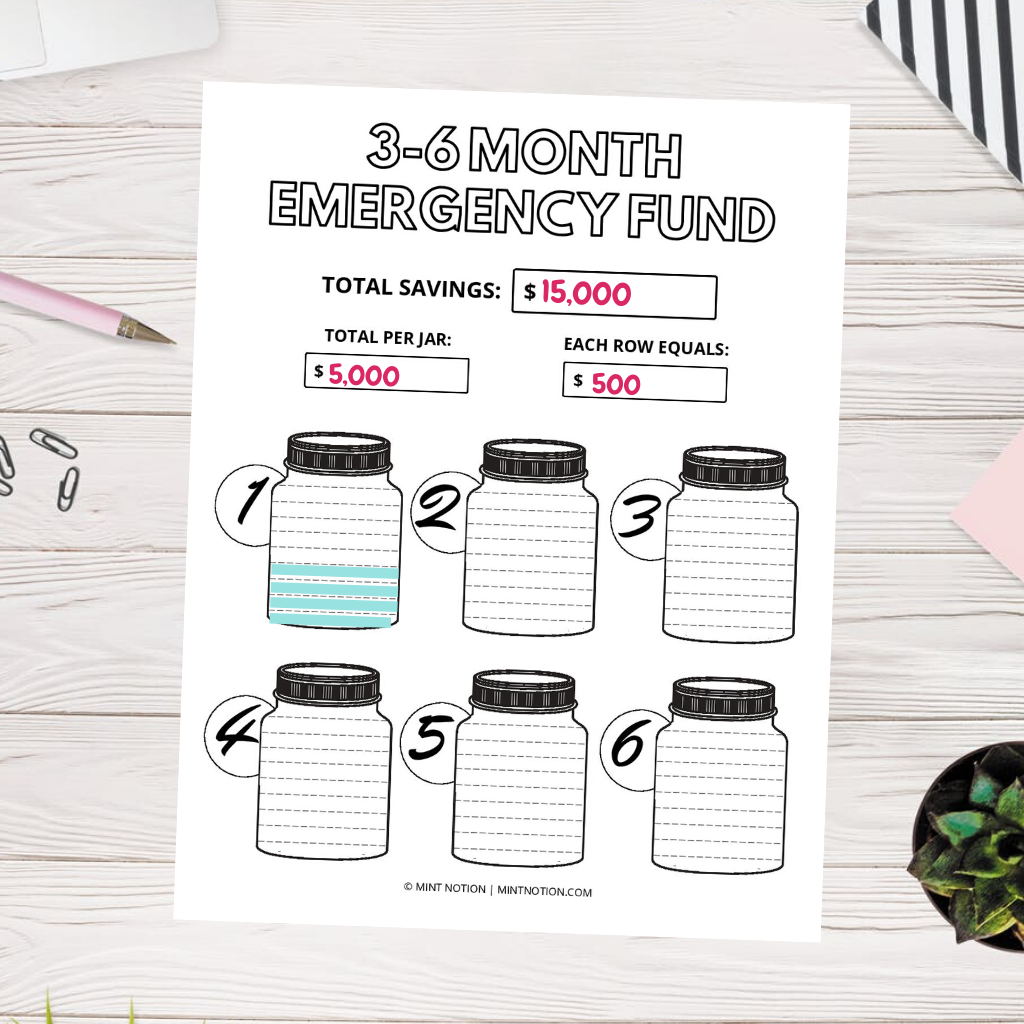
The idea behind creating an emergency fund is to have enough savings on hand so that you don’t have to rely on credit cards, loans or other forms of debt when faced with unexpected expenses. The goal should be to save up enough money in your emergency fund so that you can cover three-to-six months’ worth of essential living expenses if needed.
Why Do You Need an Emergency Fund?
Having an emergency fund provides peace of mind knowing that you are prepared for any unexpected situations and won’t have to worry about how they will affect your finances in the long run. It also helps prevent additional stress and anxiety associated with debt accumulation or missed bill payments.
Without one, even small emergencies such as a broken phone screen could derail your entire budget and put you into debt. Having an emergency fund helps prevent these types of incidents from becoming major setbacks by providing a safety net that allows you to handle them comfortably without compromising other aspects of your financial life.
How Much Should You Save in Your Emergency Fund?
The amount you need depends largely on individual circumstances such as income level, monthly expenses and family size. As mentioned earlier though most experts recommend aiming for three-to-six months’ worth of living expenses saved up in case something happens.
To calculate this amount, add up the total of your essential monthly expenses such as rent/mortgage, utilities, food and transportation. Once you have this figure, multiply it by three to get a ballpark estimate of how much you should save for a bare minimum emergency fund.
If possible though try to aim for six months’ worth of living expenses in your emergency fund instead. This will provide greater peace of mind and allow you more time to find alternative sources of income if needed.
How Can You Build an Emergency Fund?
Building an emergency fund can feel overwhelming at first but there are several steps that you can take to make it easier:
1. Set a Savings Goal: Determine how much money you want to save and set a deadline for when you want to reach that goal.
2. Create a Budget: Review your current spending habits and identify areas where you can cut back so that you can allocate more funds towards saving.
3. Automate Your Savings: Consider setting up automatic transfers from your checking account into your savings account each month so that the process becomes effortless.
4. Use Windfalls Wisely: When unexpected windfalls such as tax refunds or bonuses come in, use them wisely by adding them directly into your emergency fund rather than using them on non-essential purchases or experiences.
Where Should You Keep Your Emergency Fund?
It’s important to keep your emergency fund separate from other accounts so that it is easily accessible in case of emergencies without being mixed up with other funds meant for different purposes.
A high-yield savings account is typically recommended since they offer higher interest rates than traditional savings accounts which means more money earned over time while still allowing easy access when needed.
Conclusion
Having an emergency fund is not only smart financially but also provides peace of mind knowing that any unexpected situation won’t derail all the hard work put into achieving financial goals. By following these simple steps mentioned above anyone can start building their own cushion against unexpected expenses. Remember that the sooner you start building your emergency fund, the more prepared you will be if something unexpected happens in your life.