Emergency Funds: The Safety Net Your Finances Need
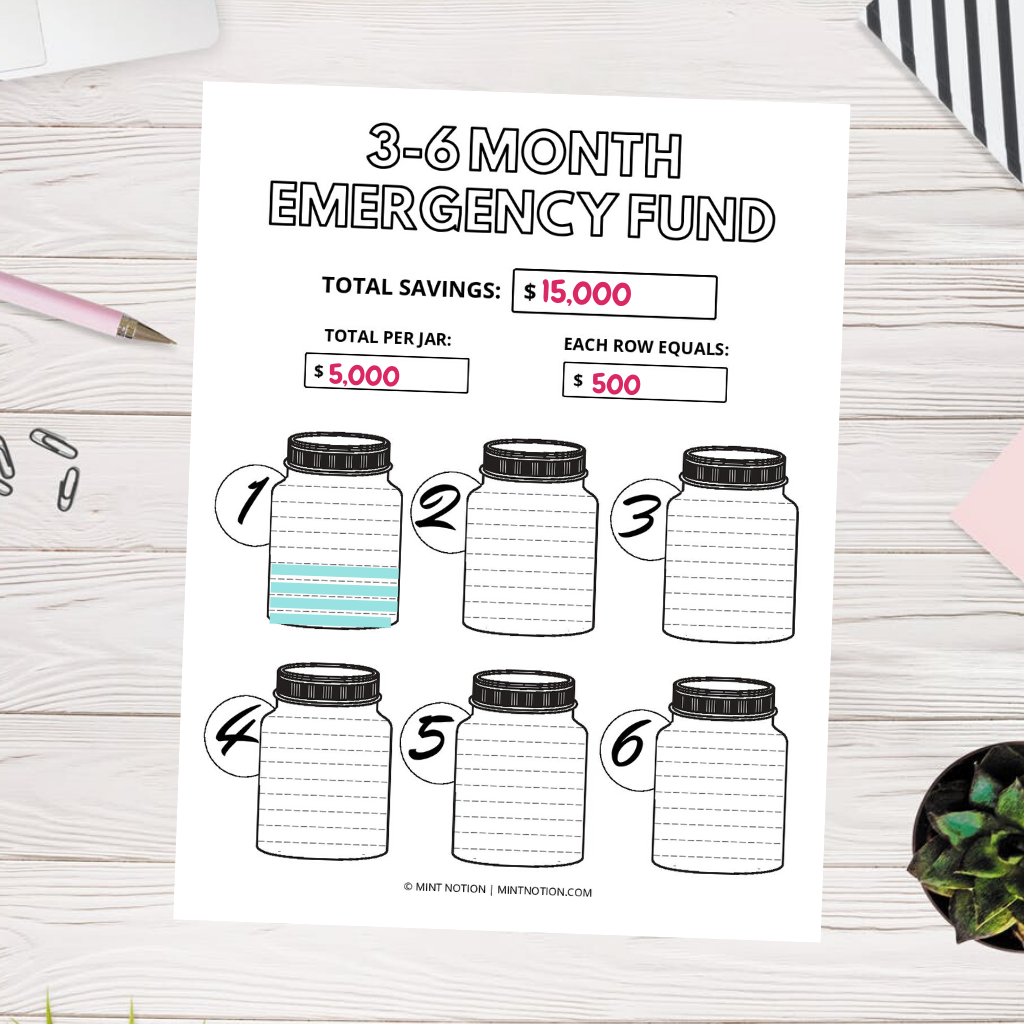
Emergency Funds: A Guide to Simplify Your Financial Life
An emergency fund is a critical component of any financial plan. It’s that safety net you can fall back on when unexpected expenses arise, such as medical bills, car repairs or even job loss. An emergency fund gives you peace of mind and helps ensure your financial stability in times of crisis.
In this guide, we’ll take a closer look at everything you need to know about emergency funds and how to create one that works for your unique situation.
What is an Emergency Fund?
Simply put, an emergency fund is money set aside specifically for emergencies. These are unforeseen circumstances that require immediate attention and often come with a significant cost attached. Examples include unexpected medical bills, sudden home repairs or job loss.
The primary goal of an emergency fund is to provide financial support during tough times without having to resort to credit cards or other high-interest loans. Without an adequate reserve of cash on hand, individuals may be forced into debt or have difficulty paying their monthly bills.
How Much Should You Save in an Emergency Fund?
Generally speaking, it’s recommended that people keep three months’ worth of living expenses in their emergency funds. This means adding up all the necessary expenses like rent/mortgage payments, utilities, groceries and transportation costs – anything that keeps the household running smoothly – then multiplying by three.
Of course, everyone’s situation is different; some people may feel more comfortable with six months’ worth of savings instead of just three. Ultimately it depends on your personal comfort level and what makes sense given your own unique circumstances.
How Do You Build an Emergency Fund?
Building an emergency fund takes time and discipline but can be done by anyone regardless of income level or financial expertise.
Here are four easy steps to get started:
1) Set a Goal: Determine how much you want/need to save based on your current monthly living expenses (as mentioned earlier). Keep this number in mind as you begin to create a budget and adjust your spending habits.
2) Create a Budget: Review your monthly bills and expenses to determine where you can cut back or eliminate unnecessary costs. Redirect these savings towards your emergency fund.
3) Start Saving: Make it a habit to save money every month, even if it’s just a small amount at first. Consider setting up automatic transfers from checking accounts into savings accounts on payday.
4) Protect Your Savings: Keep your emergency fund in an easily accessible account that earns interest but doesn’t come with penalties for early withdrawal. A high-yield savings account is often the best option since it offers competitive interest rates while allowing easy access to funds when needed most.
What Expenses Can Be Covered By An Emergency Fund?
Emergency funds should be used only for unforeseen circumstances that are necessary, urgent, and unavoidable. This includes expenses such as:
– Medical emergencies
– Job loss
– Home repairs due to natural disasters
– Car repairs after an accident
It’s important to note that emergency funds should not be used for discretionary purchases like vacations or holiday shopping sprees. Instead, these types of expenses should be planned and saved for separately.
When Should You Use Your Emergency Fund?
Knowing when to use your emergency fund can be tricky since everyone’s situation is different. However, there are some general guidelines that can help you determine whether or not dipping into your reserve makes sense:
1) When facing unexpected medical bills: If you have no other way of paying off mounting healthcare costs without jeopardizing daily necessities like rent/mortgage payments or food on the table then using some of the money set aside specifically for emergencies may make sense.
2) When dealing with job loss: Losing one’s job unexpectedly can cause significant financial strain; tapping into an emergency fund during this time may provide short-term relief until new employment opportunities arise.
3) When faced with home repairs due to natural disasters such as floods and earthquakes: Insurance may not always cover the cost of repairs, so having an emergency fund can provide a safety net to help pay for unanticipated bills.
Conclusion
An emergency fund is an essential component of any financial plan. It provides peace of mind and helps ensure that unexpected expenses don’t derail your finances. By following the steps outlined in this guide, you’ll be well on your way to building a robust reserve of cash that will protect you during tough times. Remember, it’s never too early or too late to start saving – so get started today!