Renting vs. Owning: Which is the Smarter Financial Move?
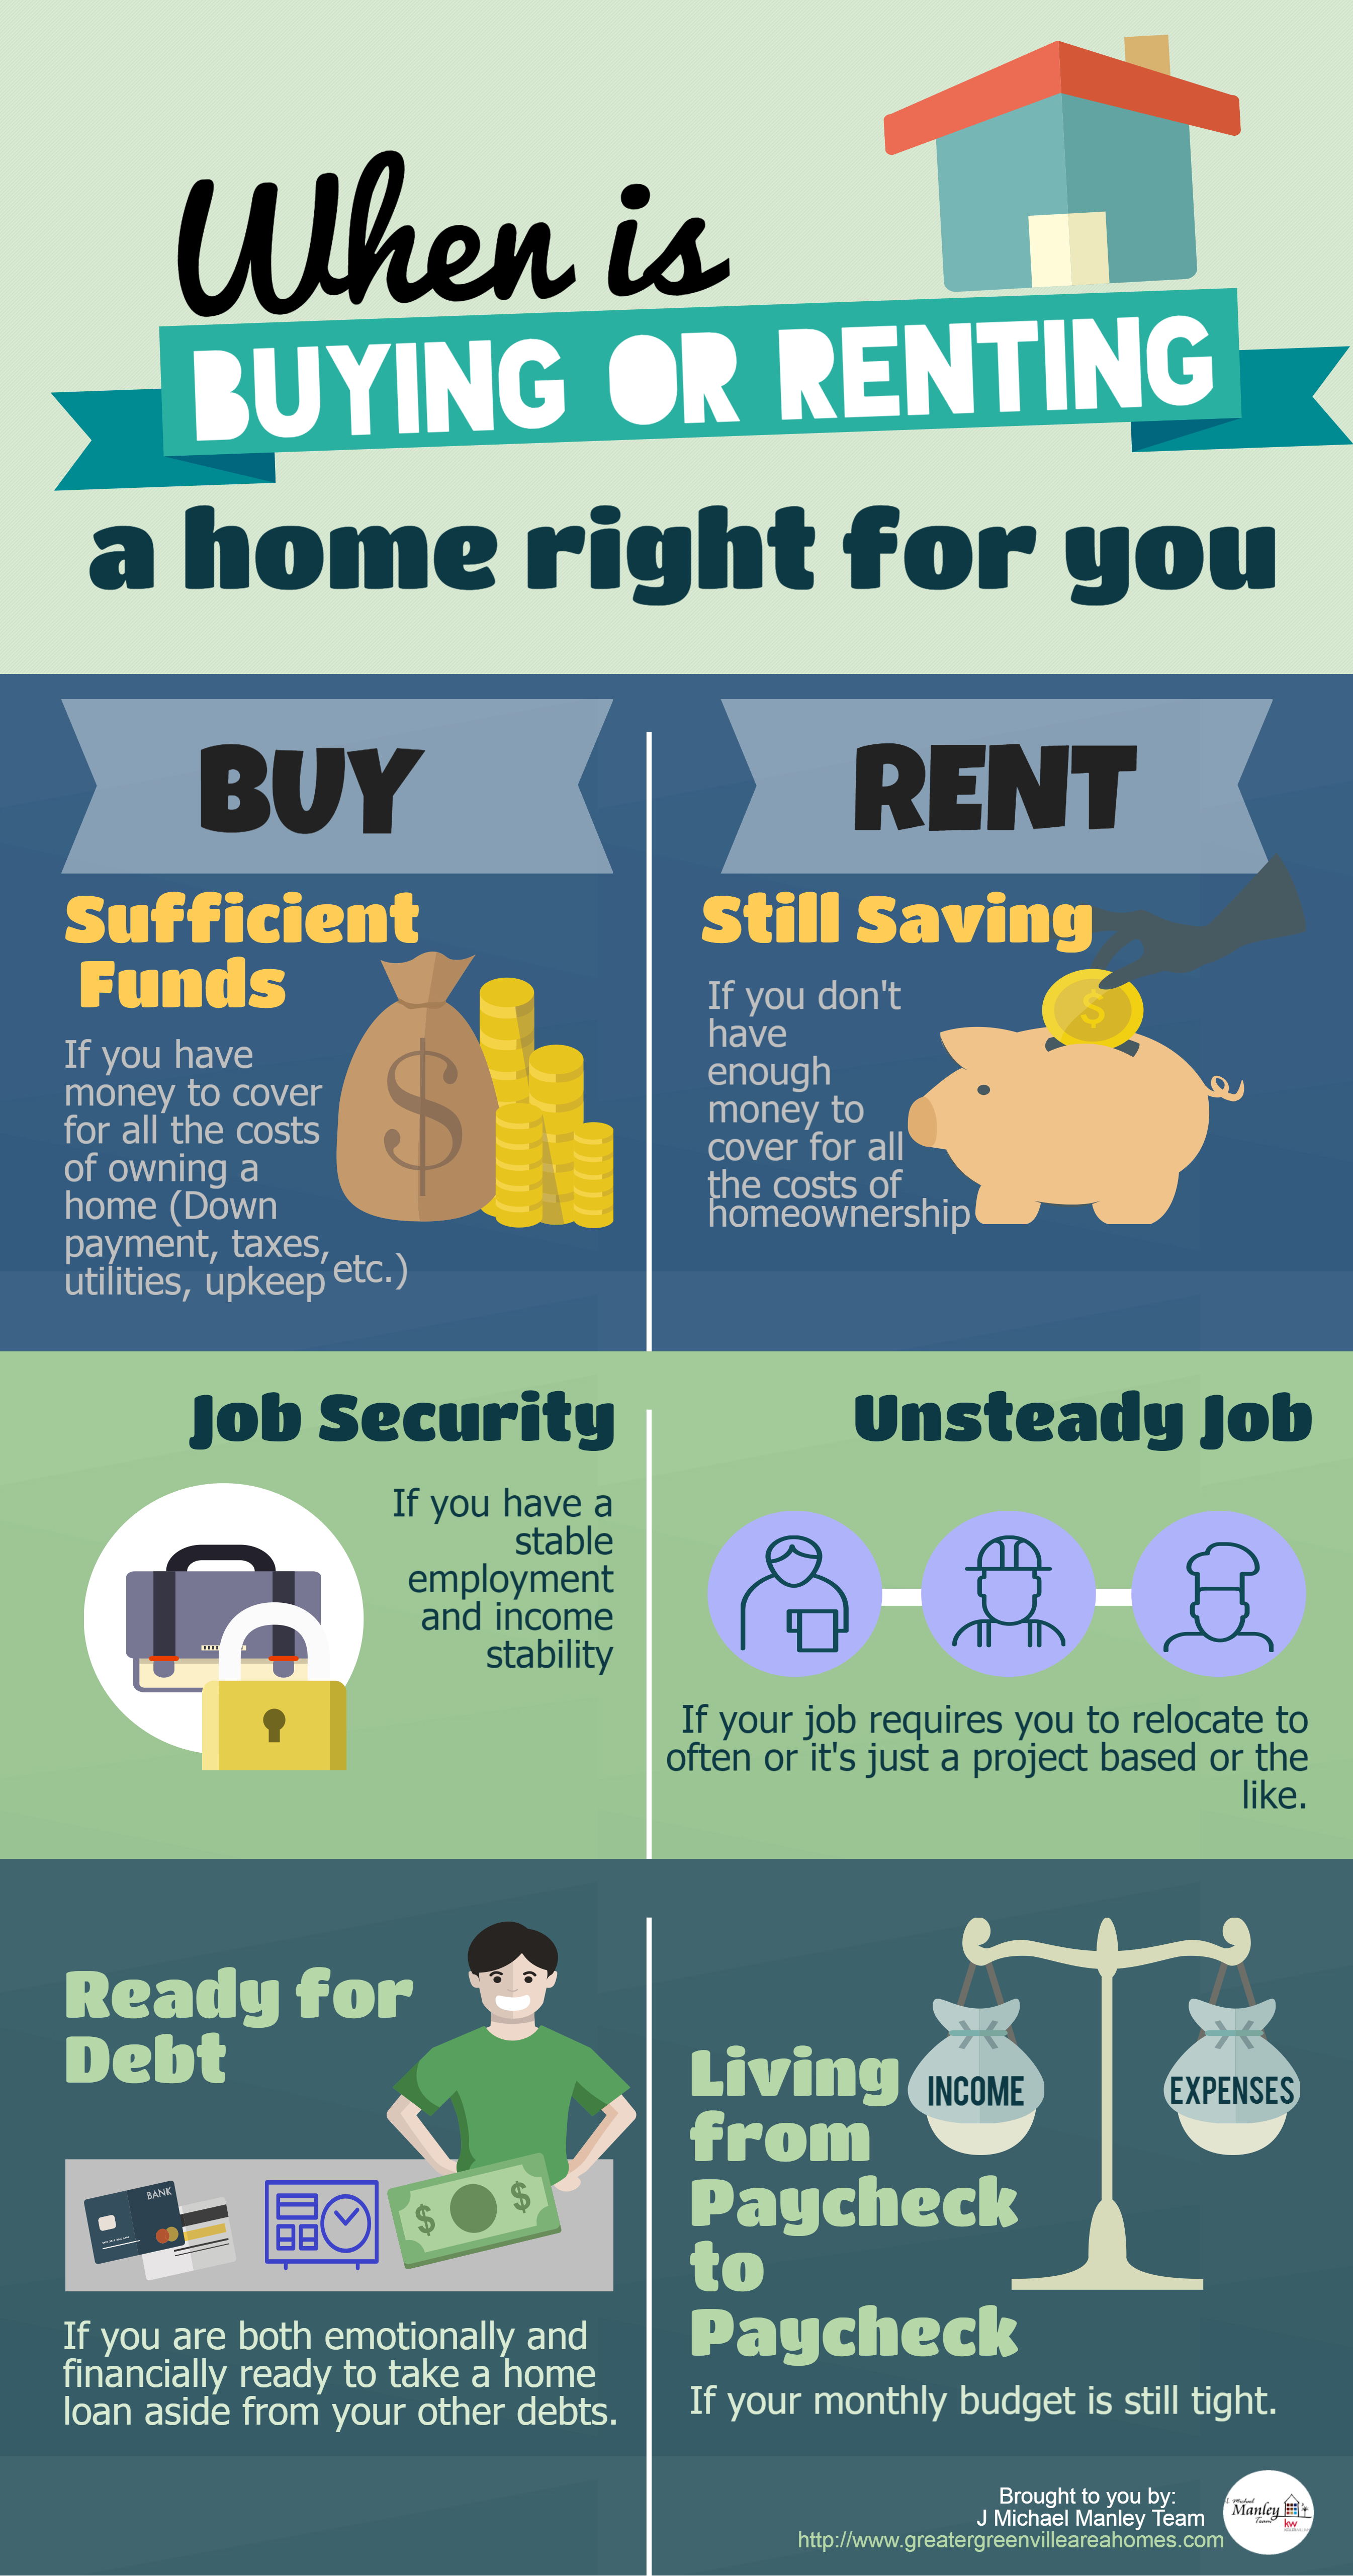
Renting vs. Owning a Home: A Financial Perspective
Introduction:
When it comes to housing, one of the fundamental decisions we face is whether to rent or buy a home. While owning a home has long been considered a significant milestone and an investment, renting offers flexibility and freedom from many financial responsibilities associated with homeownership. In this article, we will explore the financial aspects of renting versus owning a home to help you make an informed decision.
Upfront Costs:
One of the main advantages of renting is the significantly lower upfront costs compared to buying a home. When renting, you typically need to pay for security deposits and possibly first and last month’s rent. On the other hand, purchasing a house involves various expenses such as down payments, closing costs, property inspections, and appraisals.
While these upfront costs may seem daunting for potential homeowners, they can be viewed as an investment in building equity for your future. However, if you prefer immediate access to living space without committing substantial sums upfront, renting may be more suitable for your current financial situation.
Monthly Expenses:
Another crucial factor when considering whether to rent or own is monthly expenses. Rent payments are relatively fixed over time unless there are annual increases specified in the lease agreement. These predictable payments provide stability and allow for easier budgeting.
In contrast, mortgage payments often fluctuate due to interest rates changes or adjustments in property taxes and insurance premiums. Additionally, homeowners must bear maintenance costs themselves while renters can rely on landlords or property managers to handle repairs and general upkeep.
It’s important not just to consider mortgage payments but also take into account additional expenses like homeowner’s association (HOA) fees (if applicable), utilities bills that might increase compared with what you were paying as a tenant since homes tend to have more square footage than apartments or rental properties.
Building Equity vs. Investing Elsewhere:
Owning real estate provides an opportunity for individuals to build equity over time. As you pay down your mortgage, the value of your home may appreciate, allowing you to potentially sell it for a profit in the future. Homeownership can be seen as a long-term investment that contributes to personal wealth accumulation.
However, it’s essential to consider alternative investments when comparing renting with owning from a financial perspective. By choosing not to invest in real estate, individuals have the opportunity to allocate their capital into other investment vehicles such as stocks, bonds, or starting a business.
Renting provides financial flexibility and liquidity since you are not tied up in an illiquid asset like real estate. This flexibility allows renters to seize opportunities quickly or adapt their living arrangements based on changing circumstances or job locations without being burdened by property ownership responsibilities.
Tax Implications:
Homeownership comes with certain tax benefits that renters do not enjoy. Mortgage interest payments and property taxes are generally tax-deductible expenses for homeowners who itemize deductions on their tax returns.
While these deductions can help reduce taxable income for homeowners, they should only be considered after weighing all other factors involved in purchasing a home. It is advisable to consult with a tax professional regarding individual circumstances and potential savings before making any decisions solely based on tax implications.
Conclusion:
In conclusion, renting and owning both have unique financial advantages and disadvantages that should be carefully evaluated before making a decision. Renting offers more flexibility upfront costs while avoiding maintenance responsibilities but lacks the long-term equity-building potential of homeownership.
On the other hand, owning a home provides stability and an opportunity for wealth accumulation through equity growth but requires substantial upfront costs and ongoing maintenance expenses.
Ultimately, the decision between renting versus owning depends on various factors such as personal goals, financial situation, lifestyle preferences, and housing market conditions. It is important to consider both short-term needs and long-term aspirations when choosing which path best aligns with your overall financial strategy.